Quick answer: Some booking platforms now lend to salons based on their own payment data. Fresha says its Fresha Capital program has issued more than $20 million, with offers averaging about 65% of a business's monthly takings. A loan like this suits equipment only if the service it adds can repay the loan in an ordinary week, not just your busiest one.
What Fresha announced
Fresha, the salon and spa booking platform, says Fresha Capital, the in-app financing program it runs with payments company Adyen, has passed $20 million in loans to beauty and wellness businesses since launching in early 2026, and that more than 80% of borrowers have come back for more financing (Fresha, PR Newswire, Oct. 21, 2026). According to the same release, offers average about 65% of a business's monthly takings, and the program is available in the United States and Canada, among other markets.
Fresha's analysis of financing across 1,546 providers found inventory purchases, day-to-day cash flow, renovations and equipment upgrades among the most common reasons businesses borrowed. The release also says Fresha is developing financing of up to $500,000 for multi-location and enterprise groups (Fresha, PR Newswire, Oct. 21, 2026).
Why booking-platform loans feel different
A loan offer that appears inside the software you already open every morning is easy to accept. The platform already sees your sales, so there is little paperwork. That convenience is the reason to slow down: the offer is sized to what you have taken in, not to what a particular purchase will earn you.
So the useful question for a nail salon owner isn't "can I get the money?" It's "will this purchase bring in enough new money to repay the loan on time?" Equipment that just replaces something you already have doesn't add income. Equipment that lets you sell a new, priced service can.
The payback check before you tap "accept"
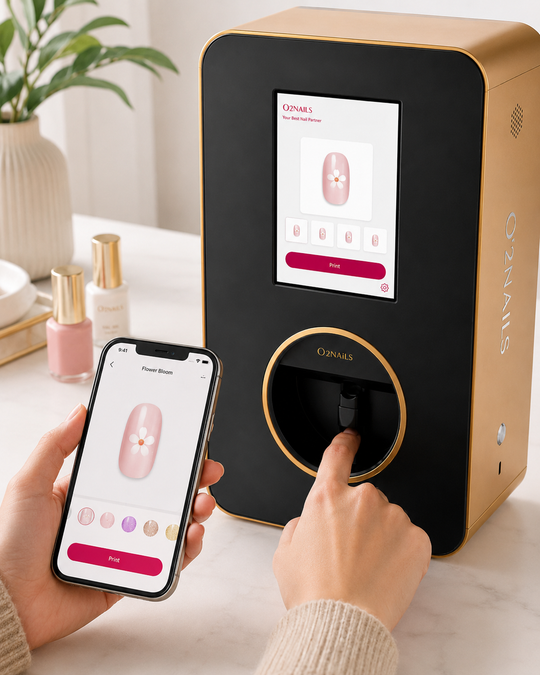
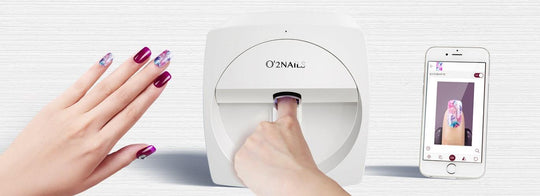
Equipment that adds a priced service is the easiest case to check, and a nail printer is a good example. Do the math with your own numbers:
- Write down what you would charge for the new add-on.
- Subtract the per-service running cost, mainly ink and supplies.
- Multiply by the number you would realistically sell in a normal week, not a holiday week.
- Multiply by the number of weeks in the repayment term, and compare the result with the total you would repay.
If the total only works out at your busiest weeks, the loan is too big or the purchase is wrong for now. For the running costs and first-year figures on a nail printer, see what it really costs to run a nail printer in a salon for a year.
One more check: make sure the new service fits into chair time you already have. An add-on that pushes out a full-price appointment earns less than it seems.
Compare it with your other options
Before you accept, read the platform's full cost and repayment terms, and set them against the other ways to pay: cash you already have, a bank or equipment loan, or a payment plan from the supplier. If you're looking at a nail printer, NailPrinter.ca is the only official O'2Nails distributor for Canada and the USA, and the payment options page explains what may be available at checkout. Whichever route you take, compare the total you will pay, not just the speed of getting the money.
Takeaway
A fast loan from your booking software is fine for equipment that sells a new service, as long as a normal week covers the repayment.